One of the most common homebuying myths is that you need a 20% down payment…
How Long Does Mortgage Approval Take? What Most Lenders Won’t Tell You
How Long Does Mortgage Approval Take? An Experienced Mortgage Broker Explains
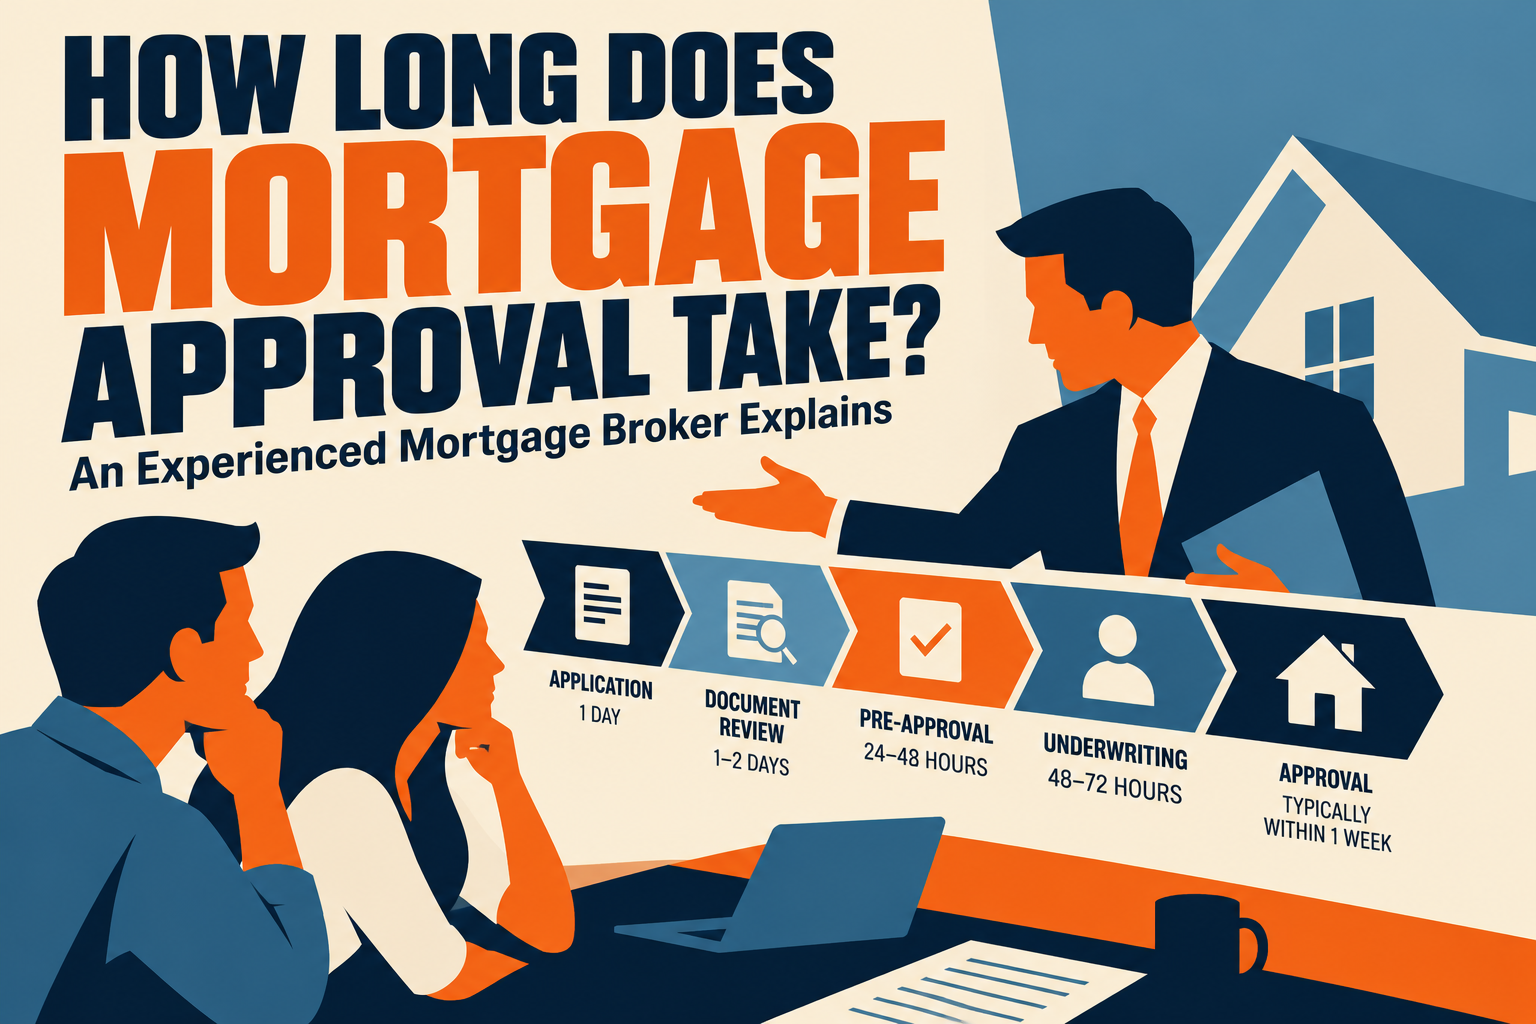
Mortgage pre-approval typically takes 24–48 hours, while initial underwriting generally takes another 48–72 hours after the lender receives a complete loan file. The entire mortgage process usually takes longer because the lender must also review the property, title, and final closing requirements.
But after 23 years in mortgage lending and more than 1,000 closed loans, I’ve learned something important: Fast mortgage approval isn’t just about how quickly a lender works. It’s about how thoroughly your loan officer prepares your application.
Many closing delays happen because problems that could have been identified during pre-approval aren’t discovered until underwriting.
Here’s how mortgage approval works, what causes delays, and how to get through the process with fewer surprises.
How Long Does Each Stage of Mortgage Approval Take?
1. Mortgage Pre-Approval: 24–48 Hours
A thorough mortgage pre-approval typically takes 24–48 hours after the borrower submits the necessary documentation.
Unlike a basic pre-qualification, a strong pre-approval involves reviewing supporting financial documents, including:
- Recent pay stubs and W-2 forms.
- Bank statements showing available funds.
- Tax returns when applicable, especially for self-employed borrowers.
- Credit history and existing debts.
- Employment history and additional income sources.
The loan officer then submits the application information to an Automated Underwriting System (AUS), which evaluates the application against applicable mortgage guidelines.
Conventional loans generally use Fannie Mae’s Desktop Underwriter or Freddie Mac’s Loan Product Advisor. FHA and VA loans also have automated underwriting processes incorporating their respective program requirements.
Although automated findings can be generated quickly, they’re only as reliable as the information entered.
An automated underwriting recommendation is not a final loan approval.
This is why the experience of the loan officer reviewing your application is so important.
2. Initial Underwriting: 48–72 Hours
Once you’re under contract and your complete loan application is submitted, the lender’s underwriter independently reviews your financial qualifications.
In my experience, initial underwriting typically takes approximately 48–72 hours, although timelines vary by lender and loan complexity.
The underwriter examines your income, employment, credit, debts, assets, and supporting documentation.
The lender may then issue:
- Conditional approval: The loan can proceed once outstanding requirements are satisfied.
- Suspension: Additional information or documentation is needed before a decision.
- Denial: The application doesn’t meet the lender’s requirements.
Most mortgage approvals involve some conditions. The key is whether those conditions are routine or involve significant problems that should have been caught earlier.
3. Clear to Close: Usually Within Days of Closing
Clear to close means the lender has satisfied its final underwriting requirements and authorized the loan to proceed toward closing.
This includes reviewing more than just the borrower’s finances.
The lender must also address:
- Property appraisal requirements.
- Title and outstanding liens.
- Property condition concerns.
- Remaining underwriting conditions.
- Final employment verification.
One reason clear to close often occurs shortly before closing is that lenders may verify employment again near the closing date.
I’ve seen otherwise completed loans delayed because an underwriter couldn’t reach the borrower’s employer.
In rare circumstances, clear to close may even be issued on the scheduled closing day.
Pre-Qualification vs. Pre-Approval: What’s the Difference?
These terms are sometimes used interchangeably, but they shouldn’t necessarily mean the same thing.
Pre-qualification is generally an initial estimate of what you might qualify for based on information you provide. That information may not have been fully verified.
Pre-approval should involve a more comprehensive review of your financial documentation, credit, income, assets, and potential underwriting concerns.
At Capital Home Loans, we focus on providing thorough pre-approvals rather than simply generating letters.
Why?
Because the most important time to identify mortgage qualification problems is before a buyer makes an offer on a home.
Once you’re under contract, financing problems can affect your closing deadline, earnest money, and ability to complete the purchase.
A thorough pre-approval can’t guarantee final approval, but it can substantially reduce the likelihood of unexpected problems.
What Causes Mortgage Approval Delays?
After closing more than 1,000 mortgage loans, I’ve noticed that many underwriting delays have something in common: Important information was missed at the beginning.
Here are some common examples.
Incomplete Employment History
A borrower might report 18 months at their current job without providing complete information about previous employment.
That doesn’t automatically disqualify them, but additional verification may be necessary.
An experienced loan officer knows which questions to ask about employment gaps, job changes, and income stability before submitting the loan.
Unexplained Bank Deposits and Missing Funds
Bank statements often reveal issues that can affect mortgage qualification.
Examples include:
- Large or irregular deposits.
- Transfers without clear documentation.
- Payments suggesting undisclosed debts.
- Insufficient funds for closing.
- Gift funds that haven’t been properly documented.
Not every unusual transaction creates a problem. But identifying transactions that require explanation early can save considerable time.
Incorrect Income Calculations
This is particularly important for self-employed borrowers and applicants receiving overtime, commissions, bonuses, or other variable income.
Mortgage qualifying income isn’t always the same as the amount someone earns or deposits into their bank account.
Different loan programs have specific requirements for calculating income.
A loan officer who doesn’t understand those requirements may issue a pre-approval based on income the underwriter ultimately cannot use.
Property and Title Issues
Even financially qualified borrowers can experience delays involving the property.
Potential problems include:
- Appraisal or property condition concerns.
- Solar equipment liens.
- Outstanding liens or title defects.
- Repairs required before closing.
These issues aren’t always predictable, but identifying potential concerns early can help prevent last-minute surprises.
Real Mortgage Approval Stories From Capital Home Loans
Two recent transactions demonstrate why experience and access to different mortgage programs matter.
Case Study 1: Self-Employed Borrower Approved After Another Lender Couldn’t Help
We recently worked with a borrower who had been self-employed for just under two years.
The borrower had strong deposits into their business bank account over the previous 12 months, but their existing lender couldn’t approve them using its available loan programs.
Instead of treating that as the end of the road, we evaluated alternative financing options.
We identified a bank statement mortgage program that allowed the borrower’s income to be evaluated using business deposits rather than relying exclusively on traditional tax-return calculations.
We were able to obtain an immediate approval through the alternative program.
Bank statement mortgages aren’t appropriate for everyone, and they may have different rates, down payment requirements, and eligibility standards.
But this example demonstrates an important point: Being unable to qualify with one lender doesn’t necessarily mean you can’t qualify for a mortgage.
Case Study 2: Switching Lenders and Closing in Two Weeks
Another client was already approved with a different lender and well into the homebuying process.
After comparing mortgage options, they discovered Capital Home Loans could offer a significantly lower interest rate.
The concern was timing. Could they switch lenders without missing their closing date?
My team and I reviewed the transaction, coordinated the underwriting requirements, and successfully completed the new loan in approximately two weeks.
The client closed on time while saving money on their mortgage rate and fees.
Not every transaction can close that quickly, but this illustrates the value of working with an experienced team that knows how to manage tight deadlines.
How to Get Your Mortgage Approved Faster
My most important recommendation is simple:
Choose an experienced loan officer who thoroughly reviews your application without taking shortcuts.
The shortcuts taken during pre-approval are often discovered during underwriting, when there’s less time to resolve problems.
Here are several ways borrowers can help keep their approval on schedule.
Get Fully Pre-Approved Before Shopping
Don’t rely exclusively on an instant online pre-qualification.
Have your supporting financial documents reviewed before making an offer, particularly if you have variable income, self-employment, employment gaps, or a complicated financial history.
Be Completely Accurate About Your Finances
Borrowers sometimes estimate employment dates, forget financial obligations, or overlook important information because they don’t realize how precise mortgage underwriting requirements can be.
An experienced loan officer understands this and knows how to ask the right questions.
Disclosing financial circumstances early is almost always easier than explaining them days before closing.
Submit Complete Documents Promptly
When your loan officer requests documentation, provide complete records as quickly as possible.
Missing statement pages, incomplete income documentation, and delayed responses can create unnecessary underwriting conditions.
Avoid Financial Changes Before Closing
Discuss significant financial decisions with your loan officer before making them.
Examples include opening new credit accounts, financing a vehicle, changing employment, or moving substantial funds between accounts.
These changes don’t automatically prevent approval, but they may require additional underwriting review.
Does the Mortgage Program Affect Approval Time?
Yes. Different loan programs have different documentation and underwriting requirements.
- Conventional loans: Typically follow Fannie Mae or Freddie Mac requirements and often use automated underwriting.
- FHA loans: Include FHA-specific underwriting and property requirements but can often follow timelines similar to conventional loans.
- VA loans: Include VA eligibility and underwriting requirements, with timing dependent on the transaction.
- Non-QM and bank statement loans: Offer alternative qualification methods for certain borrowers, particularly those with complex income documentation.
Choosing the right mortgage program early can be just as important as how quickly the application is processed.
Why Your Loan Officer Matters as Much as Your Lender
Most borrowers begin comparing mortgage companies by looking at interest rates.
And they should. Rates and closing costs matter.
But rate shopping alone doesn’t tell you whether you’re working with a knowledgeable, experienced loan officer.
Even within the same mortgage company, loan officers can have vastly different levels of experience.
One may have handled hundreds of complicated transactions. Another may have very little experience evaluating self-employment income, unusual assets, or challenging underwriting scenarios.
Both may offer the same mortgage products, but your experience could be dramatically different.
A great rate means very little if your loan doesn’t make it to closing.
Research the Individual Loan Officer, Not Just the Company
When reading mortgage company reviews, look for customers who mention your specific loan officer by name.
Pay attention to whether previous borrowers describe:
- Strong communication and responsiveness.
- Experience handling complicated financial situations.
- Problems being resolved before closing.
- Accurate information about rates and fees.
- Successfully meeting closing deadlines.
If you have a complicated financial situation, ask the loan officer about their experience handling similar loans.
The individual responsible for your mortgage can have a significant impact on whether your transaction goes smoothly.
Frequently Asked Questions About Mortgage Approval
Can You Get Mortgage Pre-Approval in One Day?
Yes. Some borrowers can receive pre-approval within one business day. At Capital Home Loans, a thorough pre-approval generally takes 24–48 hours after receiving the required documentation.
How Long Does Mortgage Underwriting Take?
Initial underwriting typically takes approximately 48–72 hours in our experience, although lender workloads, loan complexity, and outstanding conditions can extend the timeline.
Can a Mortgage Be Denied After Pre-Approval?
Yes. A pre-approval isn’t a guarantee of final approval. Changes in employment, undisclosed debts, incorrect income calculations, or property-related problems can affect eligibility.
Can I Get a Mortgage With Less Than Two Years of Self-Employment?
Potentially. Some borrowers may qualify through traditional program exceptions or alternative financing, including bank statement mortgage programs. Eligibility depends on the individual circumstances and program guidelines.
Can I Switch Mortgage Lenders Before Closing?
Yes, but timing is important. The new lender must complete its own approval process. We’ve helped borrowers switch lenders and close in approximately two weeks, although results depend on the transaction.
Final Thoughts: Mortgage Approval Starts With the Right Loan Officer
After 23 years in mortgage lending and more than 1,000 closed loans, I’ve learned that the most reliable way to accelerate mortgage approval is to identify potential problems before they reach underwriting.
A thorough pre-approval can provide buyers with greater confidence, reduce unexpected conditions, and help protect their closing timeline.
When comparing lenders, look beyond interest rates and company advertising. Research the individual loan officer handling your mortgage and make sure they have the experience your situation requires.
The right loan officer doesn’t just help you get approved. They help you avoid problems you may never have known were coming.
Get Pre-Approved With Capital Home Loans
At Capital Home Loans, the focus is on providing thorough mortgage pre-approvals, competitive financing options, and experienced guidance throughout the mortgage process.
Whether you’re purchasing your first home, self-employed, comparing lenders, or working toward a tight closing deadline, our team can help evaluate your options.
- Check current mortgage rates — No credit check or application required to view rates.
- Read our client reviews — See what previous borrowers have experienced.
- Contact Capital Home Loans — Schedule a conversation about your mortgage options.
Capital Home Loans LLC | NMLS #2577078
Approval timelines are estimates and vary by lender, loan program, borrower qualifications, and property requirements. Pre-approval does not guarantee final loan approval.

Related Posts