Welcome the Changing Season with Smart Financial Moves As we stand on the cusp of…
How to Get the Lowest Mortgage Rate: 7 Steps From a Mortgage Broker
Wondering how to get the lowest mortgage rate? Most borrowers assume it comes down to one thing: a great credit score. Credit matters, but as a mortgage broker, we see borrowers lose money far more often by getting a single quote, misunderstanding points, and focusing on the rate while ignoring the total cost. Here are the steps we walk our clients through, along with the honest opinions we’ve formed after years in this business.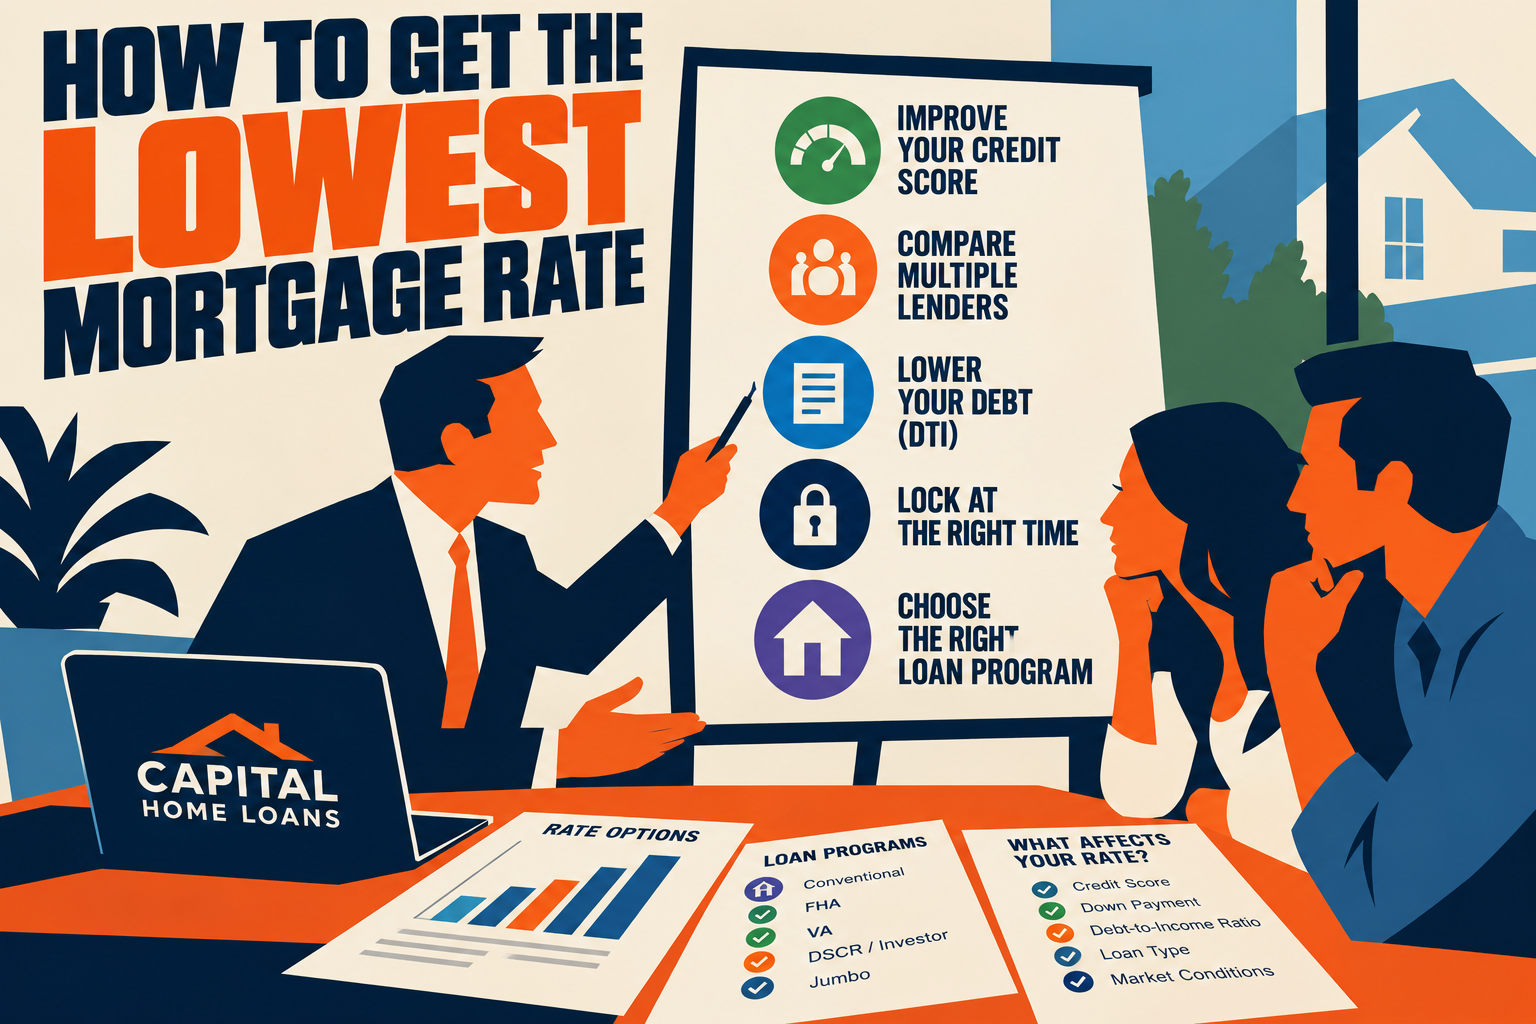
How to Get the Lowest Mortgage Rate in 7 Steps
1. Get More Than One Quote to Find the Lowest Mortgage Rate
This is the most expensive mistake we see. Freddie Mac research found that getting just one additional rate quote could save a borrower about $1,500 over the life of the loan on average, and getting five quotes saved about $3,000. Actual savings depend on your loan size and the rates available at the time. The same research found that most borrowers applied with only one lender, which means many people never test the market.
Comparing quotes is the simplest way to find the lowest mortgage rate you qualify for.
2. Don’t Let Credit Score Fears Stop You From Shopping
Many borrowers hold back because they’re afraid that comparing lenders will damage their credit. Freddie Mac’s shopping guidance recommends doing your mortgage shopping within a 45-day period to keep the effect on your credit minimal. A small, temporary dip costs far less than skipping the comparison and overpaying for years.
3. Know Where You Stand on Credit Score Tiers
Conventional loan pricing generally moves in steps rather than a smooth slope, so being a few points shy of the next tier can raise your price. Lenders also use a middle score pulled from a tri-merge credit report, and that score often differs from the free number in a banking app.
Before you apply, ask your loan officer to review how close you are to the next pricing tier. Sometimes a small step, like paying down a credit card balance before the credit pull, is worth the effort. Sometimes it isn’t, and a good loan officer will tell you which.
Knowing your tier before you apply is a quiet but powerful way to get a lower mortgage rate.
4. Understand Points and Lender Credits to Get a Lower Mortgage Rate
Most lenders quote one or two rates and leave it there. We think that leaves borrowers underinformed, so we show clients what we call a rate stack: a side-by-side view of several rate, point, and credit combinations. We walk through the numbers together so they understand the math behind each choice. Borrowers tell us this makes them feel more confident and more in control of the decision.
What Points Really Are
Paying points is pre-paid interest. You pay money up front instead of paying it over the life of the loan, trading cash now for a lower monthly payment. One point equals 1% of the loan amount.
Why Each Rate Step Costs Differently
Rates are usually offered in 0.125% increments, but each step doesn’t carry the same price. Here’s a hypothetical example on a $400,000, 30-year fixed loan (illustrative numbers, not a quote):
- Moving from 6.50% to 6.25% might cost about 1 point, or $4,000, and lower the monthly principal and interest payment by roughly $65. That’s a break-even of about five years.
- Moving from 6.50% to 6.00% might cost 1.75 points, or $7,000, and lower the payment by roughly $130. That breaks even in about four and a half years.
In this example, the bigger buy-down actually pays for itself sooner than the smaller one. You can’t see that without looking at the whole rate stack.
How Lender Credits Work
Many clients are surprised to learn that a higher rate can come with a lender credit. For example, choosing a rate about 0.25% higher might include a one-point credit, or $4,000 on this loan. That credit gets applied to your other loan costs, which lowers your upfront cash needs but raises your monthly payment by roughly $65 in this scenario.
Choosing the Right Option
There’s no universally right answer. The best choice depends on two things:
- How much cash you want to keep in reserve
- How long you expect to keep the home or the loan
If you plan to stay a long time and have the cash, buying the rate down can make sense. If you’ll likely move or refinance sooner, or you want to preserve cash, a credit may be the better fit.
5. Compare Total Cost, Not Just the Rate
A low advertised rate can hide points, higher fees, or a weak lock policy, so the rate alone doesn’t tell you what a loan really costs. When you compare Loan Estimates side by side, make sure they’re for the same loan program, the same lock period, and the same points. Freddie Mac’s guidance says the same: compare all loan terms, not only the rate. Also watch for temporary buydowns. A lender may advertise a rate that’s only in effect for the first year or two, and the payment then steps up to the full note rate, so look at what you’ll pay after the buydown ends.
A rate that looks like the lowest mortgage rate on paper isn’t always the cheapest loan once fees are added.
6. Consider using a Mortgage Broker to Compare Lenders and Find a Lower Mortgage Rate
A mortgage broker can review wholesale pricing from many lenders across the country, including household names and smaller lenders you’ve probably never heard of. Lenders also run promotions and incentives from time to time, so checking many sources helps us find the best terms for each borrower.
Why More Lenders Can Mean a Better Price
The best lender at one rate isn’t always the best lender at another. Here’s a hypothetical on a $400,000 loan:
- At 6.50%, Lender 1 offers no points, while Lender 2 charges 0.25 points ($1,000). Lender 1 wins.
- At 6.25%, Lender 1 charges 0.5 points ($2,000), while Lender 2 charges 0.375 points ($1,500). Lender 2 wins.
A single direct lender can only show you its own pricing. A broker can match each rate level with the lender offering the best price on it.
How a Broker Gets Paid
A common misconception is that a broker is a middleman you have to pay extra. In reality, a broker’s compensation comes either from the wholesale lender or from the borrower, depending on how the loan is structured. In some cases, the wholesale rate comes with a lender credit that helps cover the broker fee. Either way, the fee is disclosed on your Loan Estimate, and depending on your scenario, a broker’s pricing is often competitive with or better than going direct.
When a Broker Isn’t the Best Fit
We aren’t the right choice for every borrower. Some down payment assistance and first-time buyer programs are offered through banks or state housing agencies and aren’t available through brokers. When that’s the case, we tell clients up front and recommend they pursue that option. We’d rather point you to the best path than win every loan.
7. Don’t Try to Time the Market
Trying to time the market is usually a fool’s errand. Even the best experts can’t reliably predict the best day to lock a rate. What we can do is track trends and offer market analysis, while always reminding clients that the decision to lock is theirs.
To help, we send a daily rate update, and we offer a rate subscription portal where you enter your purchase scenario and get alerted when rates drop.
Ask About a Float-Down Option
Most lenders, including brokers, can offer a float-down if the market moves sharply in your favor after you lock. Policies vary widely from lender to lender, so read the terms before you lock.
The best way to get the lowest mortgage rate you can is to be prepared, not to predict the market.
Frequently Asked Questions
Does shopping for a mortgage hurt my credit?
Multiple mortgage inquiries made within a short window, generally around 45 days, are treated as a single shopping event for scoring purposes, so the effect is minimal.
Are mortgage points worth paying?
It depends on how long you’ll keep the loan and how much cash you want to preserve. Divide the upfront cost by the monthly savings to find your break-even point.
Do mortgage brokers cost more than banks?
Not necessarily. A broker is paid either by the wholesale lender or by the borrower, and the cost appears on your Loan Estimate. Comparing quotes shows you which is cheaper for your situation.
Should I wait for mortgage rates to drop?
No one can reliably predict the best day to lock. A rate alert, a daily rate update, and a float-down option are practical alternatives to guessing.
Ready to Get the Lowest Mortgage Rate for Your Situation?
If you’d like to see a rate stack built around your goals, view Today’s Rates or use our mortgage calculator to estimate your payment. We’ll walk you through each option so you can choose with confidence.
Capital Home Loans, NMLS #2577078. This article is for informational purposes only and is not a commitment to lend. Rates, fees, and terms vary by borrower and are subject to change without notice. Examples are hypothetical and for illustration only.

Related Posts